Kingfisher has raised its full-year profit guidance following a first half in which its two UK fascias, B&Q and Screwfix, delivered starkly different trading performances. Group adjusted pre-tax profit rose 9.9% to £404m for the six months to 31 July 2026, prompting the board to lift full-year adjusted PBT guidance to £595m–£635m, up from £565m–£625m. For BHETA members, the more instructive detail sits below the headline number: within the UK & Ireland division, Screwfix's trade-led model continues to outperform, while B&Q's core DIY business is still contending with a soft market.
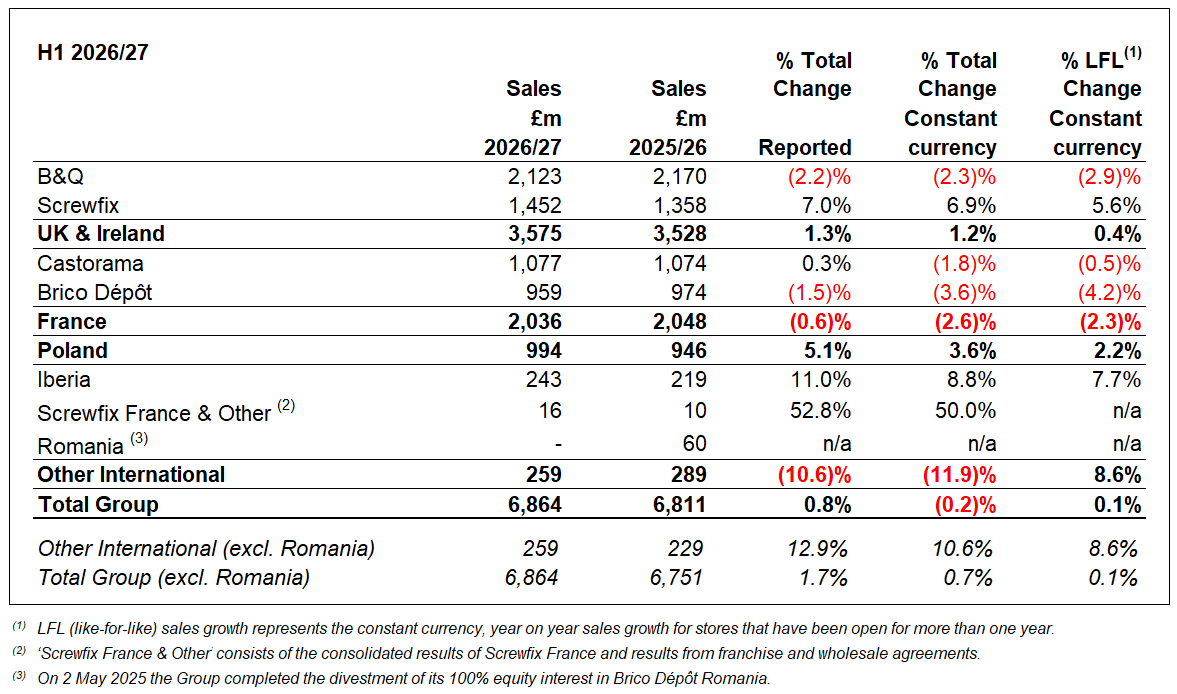
UK & Ireland total sales rose 1.3% to £3,575m, but that masks a wide divergence between the two banners. Screwfix delivered like-for-like growth of 5.6%, which Kingfisher attributes to strong volume growth, higher trade customer spend, and continued gains in customer acquisition supported by app engagement and loyalty scheme participation.
Screwfix's trade sales grew 6.1%, with trade penetration now standing at 74% of its sales, aided by the expansion of trade-specific ranges including Hager and Milwaukee. Its Rewards programme, launched in October 2025, added more than 200,000 new customers in the half and now accounts for 44% of sales, while Sprint, its rapid delivery proposition, grew 50%. Screwfix opened two net stores in the UK during the period, taking its City store format to 39 locations, and remains on track for 16 net openings across the year.
B&Q's total sales including marketplace GMS fell 0.1%, with like-for-like sales down 2.9% for the half. Kingfisher attributes this to heatwave-driven disruption, which it says shifted demand online and reduced store footfall, alongside continued softness in bathroom ranges. Market share was broadly stable, however, and B&Q's trade arm, TradePoint, outperformed the wider trade market with like-for-like growth of 0.2% and total sales of £490m, now representing 23% of B&Q's sales. TradePoint growth was underpinned by a 5.3% rise in active trade members and a 23% increase in sales from Trade Sales Partner accounts. B&Q's e-commerce sales grew 19%, with marketplace GMV up 34% to £306m, generating a retail profit contribution of £12m.
At a divisional level, UK & Ireland gross margin improved by 50 basis points, which Kingfisher attributes to product cost management and supplier negotiations, alongside the growing contribution of B&Q's marketplace and retail media, and favourable foreign exchange movements. These gains were partly offset by higher freight costs and a growing share of lower-margin trade sales. Operating costs rose 1.6%, driven by two months of higher employer National Insurance contributions, wage increases, technology investment and new store costs, though this was partly offset by structural savings from B&Q's prior-year operating model changes and a one-off £14m UK business rates refund. UK & Ireland retail profit rose 4.9% to £361m, with margin up 40 basis points to 10.1%.
Kingfisher's own statement is unambiguous about the wider backdrop: the UK home improvement market declined by low single digits over the half. Chief Executive Thierry Garnier described the period as "a solid H1 performance, growing sales, gross margin and profits through market share gains," while acknowledging the consumer environment "remains mixed."
What does this mean for suppliers?
- B&Q's core DIY sales remain under pressure from a soft UK market, while Screwfix's trade-led model continues to pull away, suppliers with a genuine trade proposition are better positioned across both fascias.
- TradePoint's above-market growth suggests B&Q's own trade push is gaining traction, even while its retail DIY business struggles, worth watching for ranging opportunities.
- Marketplace and retail media are now material profit contributors at B&Q, not just a sales channel, a trend suppliers should factor into commercial discussions.
- Higher UK employment costs (National Insurance, wages) are a real and rising cost pressure for retailers, which may feed into future negotiations on margin and pricing.
Read the full report: