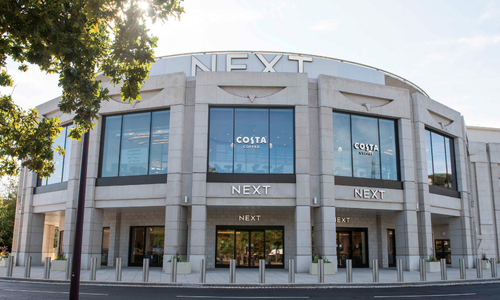
Fashion, homeware and beauty retailer Next has reported a strong first half, with group sales up 9.0% and profit before tax up 10.5%, a result that beat the company's own expectations and was driven in part by strong growth in its home and interiors-focused owned brands, offering an encouraging signal for BHETA members watching the health of UK home-related demand.
Group sales rose to £3.54bn in the 26 weeks to 1 August 2026, with profit before tax reaching £569m. Buoyed by the performance, Next raised its full-year profit guidance by £12m to £1,255m, now expecting full-year profit growth of 8.4%. UK product sales grew 3.6% against a guidance of just +1.3%, while international online sales rose 23.9%.
Next's wholly-owned and licensed brands (WOBL), including home and interiors names such as Cath Kidston, Rockett St George, Nina Campbell and Laura Ashley, grew 32% online in the UK and 82% overseas, now accounting for 9% of full-price sales, and delivering higher margins (18.8%) than the core Next brand (18.3%).
This continued expansion of home-focused owned brands suggests genuine appetite among UK and international shoppers for home and interiors ranges, even in a market where store-based general retail footfall has been softer, a positive cross-check point for BHETA members' own home and housewares performance.
Next also highlighted operational gains behind the numbers: efficiency improvements at its new Elmsall 3 warehouse helped offset wage and National Insurance cost increases, supporting a 0.3 percentage point improvement in group margin to 16.1%. A further warehouse development, Elmsall 4, is now in planning to support future growth.
On the outlook, management struck a measured but constructive tone: "We do not anticipate a precipitous decline in spending, rather a slow, steady decline as the year progresses" a comment on the wider UK economic backdrop rather than a reflection of Next's own trading, which continues to outperform its guidance.
What does this tell suppliers?
Home and interiors-branded ranges appear to be a genuine growth driver, even where general retail is more mixed, a positive signal for BHETA members in housewares and homeware.
- International online demand remains a strong growth channel, with owned and licensed brands scaling faster overseas than the core brand.
- Investment in warehouse capacity and efficiency continues at pace, pointing to retailers prioritising service levels and cost control alongside growth.
- Despite a more cautious view on the broader UK economy, the retailer's own performance suggests resilient, rather than declining, demand in home-related categories.