US home improvement retailer Lowe’s has published its third-quarter financial statements, and the headline numbers are encouraging. Sales and profit are both up on last year, costs are well controlled and the business is building stock, although margins have come under some pressure.
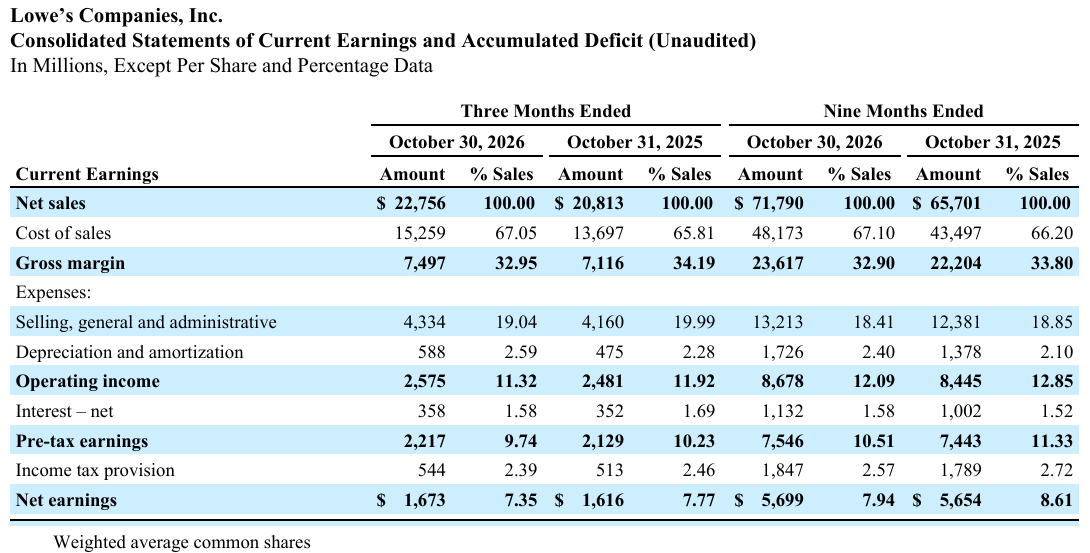
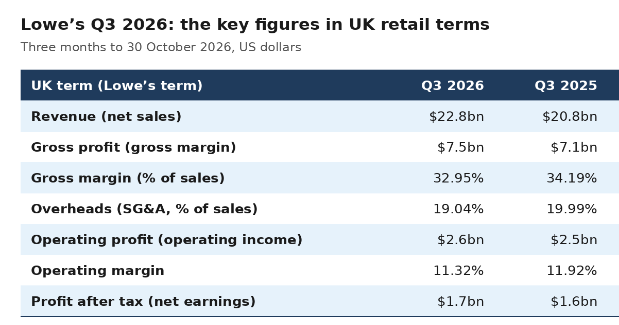
Net sales for the three months to 30 October 2026 reached $22.8 billion, up 9.3% on last year by our calculation, and sales for the first nine months of the year are also up 9.3%, to $71.8 billion. The one soft spot is gross margin, which slipped to 32.95% of sales from 34.19% a year ago.
It’s worth saying what these figures don’t include. Lowe’s financial statements give no like-for-like sales, transaction numbers, category breakdown or management commentary, so we can’t yet say how much growth came from existing stores, or why margin fell. Acquisitions also cloud the comparison: Lowe’s spent $10.1 billion buying businesses over the same nine months last year.
Tight on costs
Where Lowe’s has done well is overheads. Selling, general and administrative costs rose 4.2%, less than half the pace of sales, and fell to 19.04% of sales from 19.99%. That helped operating profit grow 3.8% to $2.6 billion, although operating margin still slipped from 11.92% to 11.32%. Net earnings rose 3.5% to $1.7 billion.
Stock is building again
For members, the balance sheet is just as interesting as the profit line. Merchandise inventory stood at $18.3 billion at the quarter end, up 6.6% year on year. The cash flow statement shows Lowe’s adding around $1.0 billion of stock over the first nine months of the year, having reduced it by about $0.8 billion over the same period last year. Accounts payable rose 7.5% to $11.0 billion, slightly ahead of inventory.
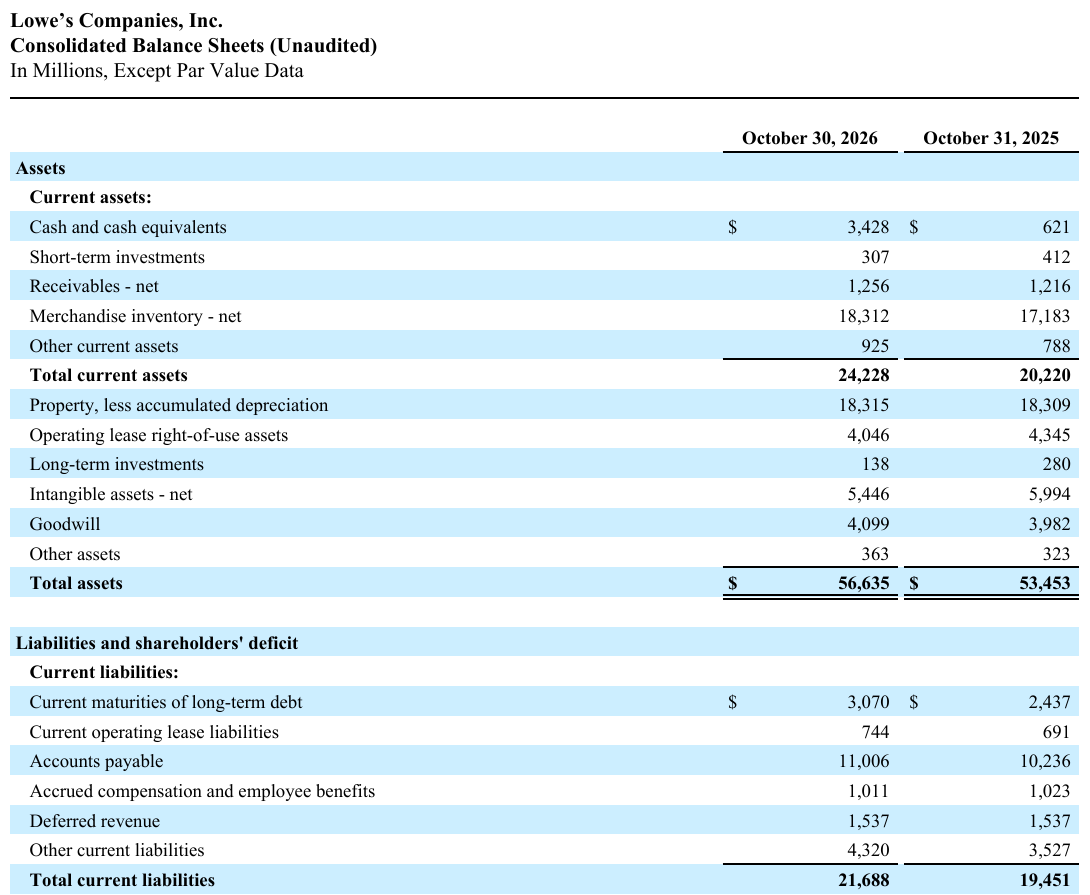
The business is also in a stronger cash position, with $3.4 billion in the bank against $0.6 billion a year ago, after repaying $2.4 billion of debt so far this year.
What does this tell UK suppliers?
- Margin pressure looks sector-wide. With both of the big US home improvement chains growing sales while gross margin falls, this looks like a market trend rather than one retailer’s problem.
- Lowe’s is restocking. Building inventory this year after cutting it last year suggests more confident ordering, at least in the US.
- Efficiency stays high on the agenda. Growth has come with tight control of overheads, and that focus on cost is unlikely to ease while margins are under strain.
- The full picture is still to come. Without like-for-like or category figures, these numbers are best read alongside Lowe’s full results commentary.